The Bull Market, a Big November & 2025 Inflation Adjustments

November was a big month for stocks! The Dow closed above 45,000 for the first time, and the S&P 500 hit 6,000 for the first time. Small-cap stocks rose almost 11% during the month.

Optimism over lower taxes, a stronger economy and strong earnings were the likely reasons for the month’s great showing. So far in 2024, the S&P has made 56 new all-time highs. The S&P is up more than 25% for the year — and for the first time since 1998, it’s up more than 20% in back-to-back years.

The current bull market is 26 months old and up more than 70% from lows in mid-October 2022. The good news is that once previous bull markets get to this point, there can still be additional room to go higher. Over the past 50 years, five other bull markets have lasted more than two years. The shortest lasted five years, and the longest lasted more than 12 years.

Bull Markets Beyond Their Second Birthday
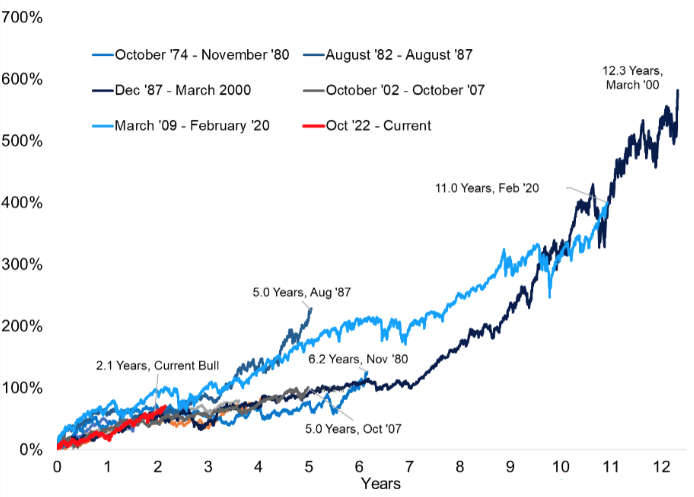
Chart showing the duration of bull markets since 1950.
Source: FactSet, Carson Investment Research 12/6/24

Here are some fun market tidbits to end the year:

1. The “Santa Claus rally” is the typically encouraging period that includes the last five trading days of December and the first two trading days of the new year.
2. December typically is the S&P 500’s second-best month in an average election year, trailing only November.
3. On average, December is the third-best month, behind April and November.
4. Going back to 1950, December has been positive 75% of the time.

Santa brings gifts — and not always in the form of market returns. The IRS recently released its inflation adjustments for 2025 related to personal income tax, retirement contributions, estate taxes and Social Security benefits. While these changes won’t affect tax returns due in April, they will be very helpful in planning for 2025.

Personal Income Tax

The standard deduction is increasing in 2025, which could mean a bigger tax break for you. The new standard deduction for 2025 is:

• Married filing jointly: $30,000, an increase of $800
• Single taxpayers and married individuals filing separately: $15,000, up $400
• Heads of Households: $22,500, an increase of $600
• In addition, retired married couples (both age 65+) filing jointly, will receive an additional standard deduction of $3,200 ($1,600 each)! This may make it more difficult to itemize deductions in 2025. We will want to keep this in mind with charitable giving to consider a bunching strategy.

For tax year 2025, the top tax rate remains 37% with income greater than $751,600 for married filing jointly ($626,350 for single taxpayers). The other tax brackets are: 

• Incomes over $501,050 for married filing jointly ($250,525 for single): 35%
• Incomes over $394,600 for married filing jointly ($197,300 for single): 32%
• Incomes over $206,700 for married filing jointly ($103,350 for single): 24%
• Incomes over $96,950 for married filing jointly ($48,475 for single): 22%
• Incomes over $23,850 for married filing jointly ($11,925 for single): 12%
• Incomes less than $23,850 for married filing jointly ($11,925 or less for single): 10% 

Retirement Savings Contributions

The 401(k)-contribution limit is increasing by another $500 to $23,500. The maximum contribution for certain profit-sharing plans is increasing to $70,000.

Traditional and Roth IRA contribution limits are staying the same at $7,000. In 2025, for those under the age of 50, the cap will remain at $7,000. Married couples with income below $236,000 will be able to make a full Roth contribution in 2025 ($150,000 for those who are single). Phaseout ranges are changed for 2025; couples with income over $246,000 will not be eligible to contribute to a Roth IRA.

While catch-up contributions for participants 50 and older will remain at $7,500, the IRS is introducing a new super catch-up contribution limit for older employees. Beginning in 2025, individuals age 60-63 can contribute an additional $3,750 to their employer-sponsored retirement plans, for a total catch-up amount of $11,250.

The backdoor Roth IRA option remains a viable choice. The first step is to contribute to a Traditional IRA; this is a non-deductible contribution. After the traditional IRA contribution is completed, you can convert those funds to a Roth IRA.

If the original contribution to a traditional IRA was not deductible, then the conversion of that amount is non-taxable. However, any growth on that amount between the contribution and the conversion dates would be taxable. Completing the backdoor Roth transaction can be a tricky process, and you will want to consult your financial advisor and CPA.

Please make sure you adjust your 401(k) plan to account for the increased contribution limit.

Social Security

Social Security benefits will increase 2.5% in 2025, an average increase of almost $48 per month. This adjustment is smaller when compared to the 5%-8% increases that were in response to higher inflation in recent years. 

Estate Taxes and Gifting

The gift tax annual exclusion is increasing from $18,000 to $19,000 for 2025, the fourth consecutive year that the gift limit has increased. Individuals can gift up to this amount to any number of individuals in 2025 without incurring gift tax or using any of the taxpayer’s lifetime exemption. Married couples can use this exemption, allowing them to gift up to $38,000 annually to each recipient in 2025.

In addition, the lifetime exemption amount increased about $380,000 per person, to $13.99 million per individual. This increase means that a married couple can shield a total of $27.98 million from federal estate or gift tax. This exemption is still set to sunset by about 50% at the beginning of 2026. Remember, however, that certain kinds of planning strategies can take months or even years to implement.
Promo for an article titled How to Make the Biggest Impact With Your Charitable Donation.

The end of the year is a perfect time to review your financial planning needs. This includes reviewing the investment portfolio, assessing year-end tax planning opportunities, reviewing retirement goals, and managing your legacy plans. The above changes for 2025 may apply to you and your family. We are happy to meet to discuss any of the above to ensure that you remain on track with your financial goals.

The CD Wealth Formula

We help our clients reach and maintain financial stability by following a specific plan, catered to each client. 

Our focus remains on long-term investing with a strategic allocation while maintaining a tactical approach. Our decisions to make changes are calculated and well thought out, looking at where we see the economy is heading. We are not guessing or market timing. We are anticipating and moving to those areas of strength in the economy — and in the stock market. 

We will continue to focus on the fact that what really matters right now is time in the market, not out of the market. That means staying the course and continuing to invest, even when the markets dip, to take advantage of potential market upturns. We continue to adhere to the tried-and-true disciplines of diversification, periodic rebalancing and looking forward, while not making investment decisions based on where we have been.

It is important to focus on the long-term goal, not on one specific data point or indicator. Long-term fundamentals are what matter. In markets and moments like these, it is essential to stick to the financial plan. Investing is about following a disciplined process over time.

Sources: Baird, Carson, Fidelity, Schwab
Year-End Suggestions to Help You Save More and Reduce Your Taxes

With the election in the rearview mirror, we are entering the home stretch for 2024. The end of the year is an important time for making financial decisions that can have an impact not only in the new year ahead, but for years to come.

As 2025 approaches, now is the perfect time to review planning strategies to ensure that your wealth plan reflects any changes in your circumstances or goals, the current tax environment and the economic landscape.

We recommend that you review the checklist below for ideas to consider and discuss.

Income Tax Strategies

1. If you anticipate your marginal income tax bracket to increase next year, you may consider accelerating income into 2024 and deferring deductions to 2025.

2. If you anticipate being in a lower tax bracket next year:

• Defer income (if possible) to postpone paying the tax and to have that income at a lower bracket.
• If you itemize on your tax return, bunch your medical expenses in the current year to meet the percentage of your adjusted gross income to claim those deductions.
• Make your January mortgage payment in December so you can deduct the interest on this year’s return.

Tax-related Investment Strategies

1. Tax-loss harvesting is the strategy of selling securities at a loss to offset a capital gain liability, either for today or in the future. Securities must be sold by Dec. 31, the last trading day of 2024, to realize a capital gain or loss.

• Harvest losses by selling taxable investments. Note: You must wait at least 31 days before buying back a holding that is sold for a loss to avoid the IRS wash-sale rule.
• Harvest gains by selling taxable investments if you have a tax loss carryforward.

2. Ensure that you have satisfied your required minimum distributions (RMD).

• If you fail to take your RMD, this may result in a 25% penalty (down from 50%). 
• If you own an inherited IRA, an RMD may be required separately for that account as well. If you inherited an IRA after 2019, the inherited IRA must be depleted by the end of the 10th year. Beginning next year, certain beneficiaries must take an annual distribution over the 10-year period following inheritance, instead of waiting to distribute the entire amount until the 10th year.

Retirement Planning Strategies

1. Maximize your IRA contributions. You may be able to deduct annual contributions of up to $7,000 to your traditional IRA and $7,000 to your spouse’s IRA ($8,000 if over the age of 50).

2. Consider increasing or maximizing your 401(k) contribution. The maximum contribution in 2024 for those under 50 is $23,000, and for those over 50, the maximum contribution is $30,500. Boosting contributions to your 401(k) can lower your adjusted gross income while increasing your retirement savings.

3. Consider making contributions to a Roth 401(k) if your plan allows.

4. Consider setting up a Roth IRA for each of your children who have earned income during the year.

Gifting Strategies

1. Consider making gifts of up to $18,000 per person as allowed under the federal annual gift tax exclusion. You can give up to $18,000 this year to as many people as you want without triggering gift taxes. Payments made directly to educational and/or medical institutions on behalf of your intended beneficiary do not count towards your annual exclusion amount — or against your lifetime estate tax exclusion.

2. Create a donor advised fund for an immediate income tax deduction and provide immediate and future benefits to charity over time.

3. If you already have a donor advised fund or want to donate to a charity, consider gifting appreciated assets that have been held longer than one year to get the fair market value income tax deduction while avoiding income tax on the appreciation.

4. If you are over the age of 70½, consider making a direct transfer from an IRA to a public charity. The distribution is excluded from gross income, and you can give up to $105,000 as a tax-free gift from your IRA that may fully satisfy RMD requirements.

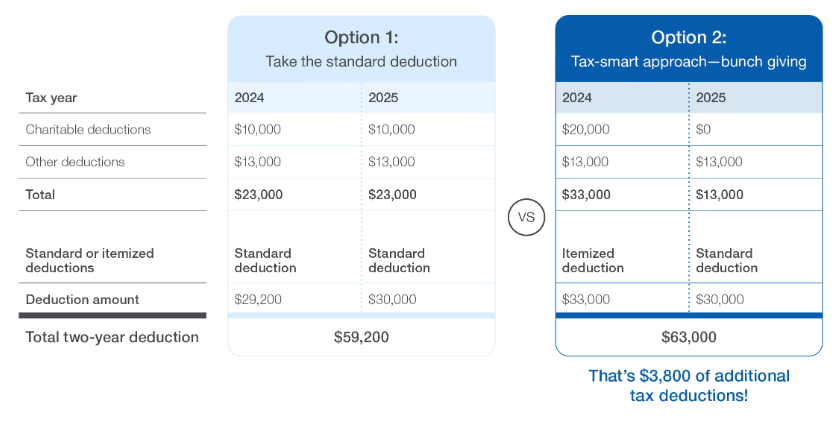
5. Consider combining multiple years of charitable giving into a single year to exceed the standard deduction threshold. This is called “bunching.” The chart below illustrates how it can reduce taxes if executed properly.

Wrapping Up 2024, Planning for 2025

1. Discuss major life events with your team at CD Wealth to confirm you have clarity in your current situation.

2. Communicate with your CPA to provide capital gains and investment income information for a more accurate year-end projection.

3. Check your Health Savings Account (HSA) contributions for 2025. If you qualify, you can contribute up to $4,300 (individual) or $8,550 (family), plus an additional $1,000 catch-up if you are over 55.

4. Double-check your beneficiary designations for retirement plans, IRAs, Roth IRAs, annuities and life insurance policies.

5. If you do not already have identity theft protection, consider purchasing a service to help protect you and your family. 

The end of the year is the perfect time to review your financial planning needs.

This includes reviewing the investment portfolio, assessing year-end tax planning opportunities, reviewing retirement goals, and managing your legacy plans.

The checklist above includes just some of the items that may apply to you and your family. We are happy to meet with you to discuss any of the above and to ensure that you stay on track with your financial goals.

Promo for an article titled How to Make the Biggest Impact with your charitable donation.

The CD Wealth Formula

We help our clients reach and maintain financial stability by following a specific plan, catered to each client. 

Our focus remains on long-term investing with a strategic allocation while maintaining a tactical approach. Our decisions to make changes are calculated and well thought out, looking at where we see the economy is heading. We are not guessing or market timing. We are anticipating and moving to those areas of strength in the economy — and in the stock market. 

We will continue to focus on the fact that what really matters right now is time in the market, not out of the market. That means staying the course and continuing to invest, even when the markets dip, to take advantage of potential market upturns. We continue to adhere to the tried-and-true disciplines of diversification, periodic rebalancing and looking forward, while not making investment decisions based on where we have been.

It is important to focus on the long-term goal, not on one specific data point or indicator. Long-term fundamentals are what matter. In markets and moments like these, it is essential to stick to the financial plan. Investing is about following a disciplined process over time.

Sources: Capital Group, Fidelity, Schwab

Election Advice for Investors: Ignore the Noise, Focus on the Big Picture

We are less than a week away from Election Day. The presidential race and the race for control of the House and Senate remain very close. There is a good chance we won’t know the outcome on Election Day, and it may take many days to count the votes.

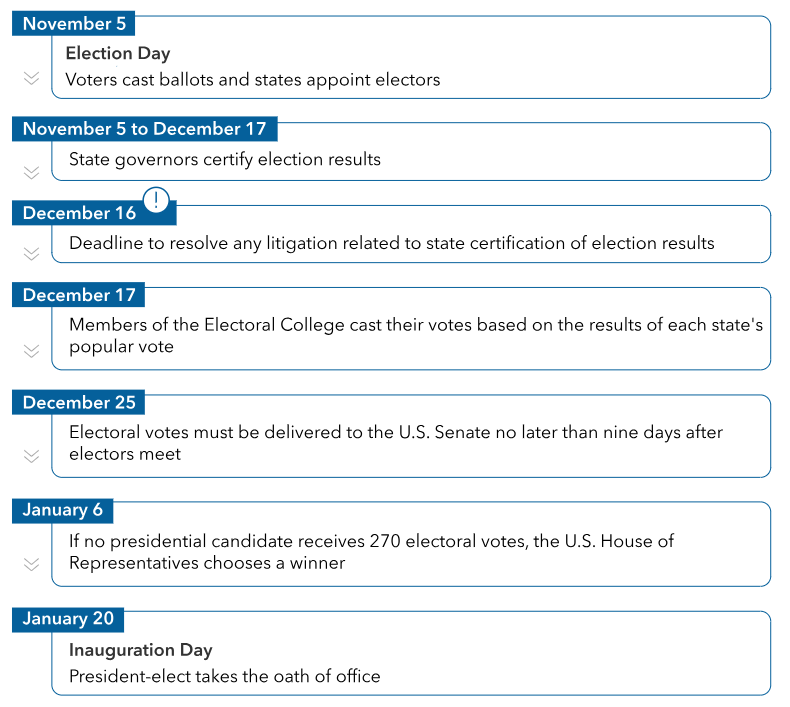
It’s possible that one candidate will gain a sizeable lead so that we will know the outcome sooner, but if not, below is a timeline for how the Presidential Election will play out over the next few months. There could be a lot of uncertainty in the days to come, and that may be reflected in a higher level of market volatility during that time.

What Happens Between Election Day and Inauguration Day

Table showing the timeline between election day and inauguration day.
Sources: Capital Group, National Archives

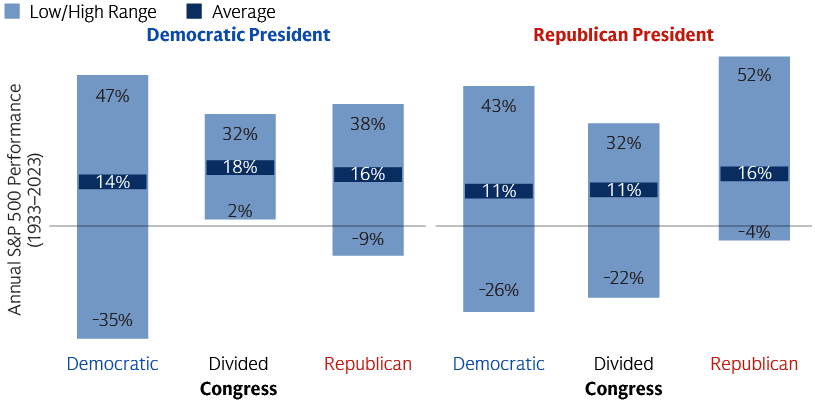
For long-term investors, it is important to keep in mind that the political structure in Washington hasn’t had much of an impact on market returns. From 1933 to 2023, under unified and split governments, the average annual return for the S&P 500 has been between 11% and 14%. Under a split Congress, as we have today, the market has generated an average return of 13.7%.

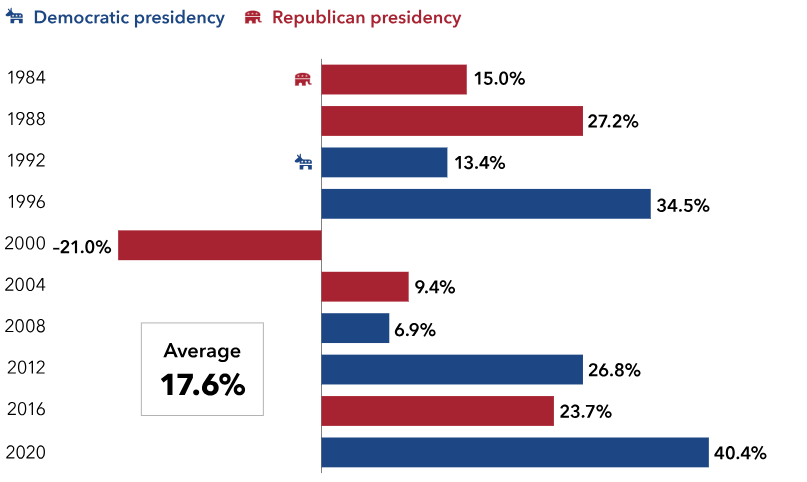
In more recent times, markets have posted even better results one year after Election Day. Since 1984, the average return a year later has been 17.6%, with only one year (2000) being negative. At the end of the day, financial markets appear to care more about the certainty of election outcomes than about who occupies the White House.

S&P 500 Index Total Returns One Year After Election

Chart showing market returns one year after elections since 1984.
Sources: RIMES, Standard & Poor’s. As of Sept. 30, 2024.

As the election cycle plays out, the noise and uncertainty can feel overwhelming and anxiety-provoking. In our view, long-term investors should ignore the noise and continue to focus on their financial goals and plan. Presidential elections historically have had very little impact on the stock market.

As we have continued to emphasize, stock markets are more influenced by corporate earnings, monetary policy and economic data than by the election outcome.

The balance of power in Congress may have much more of an effect on issues that matter to investors, such as tax policy, tariffs, the federal debt ceiling and foreign relations.

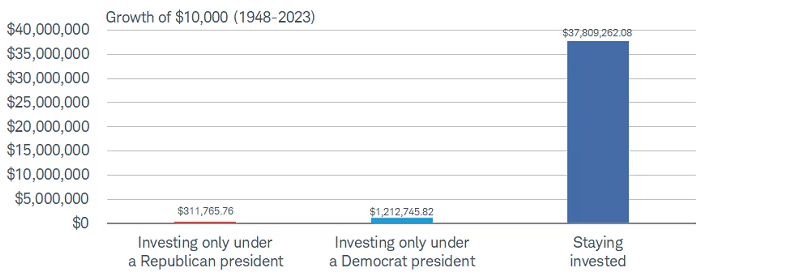
Consider the mythical investor who put $10,000 into the S&P 500 at the beginning of 1948 and did not care who was in the White House. If that investor kept their money in the market, that initial investment would grow to nearly $38 million! Had they invested the $10,000 with Republicans in office only, it would have grown into $310,000, and with Democrats in office only, the total would be $1.2 million.

Stay focused on the long-term goals and the bigger financial picture.

Time IN the Market Matters

Chart showing returns on a $10,000 investment under one or both parties in power.
Source: Schwab Center for Financial Research with data provided by Morningstar Inc. The above chart shows what a hypothetical portfolio value would be if an investor invested $10,000 in a portfolio that tracks the Ibbotson U.S. Large Stock Index on 1/1/1948 under three scenarios. The first two scenarios would occur if the investor only invested when one particular party was president. The third scenario is what would happen if an investor stayed invested throughout the entire period. Returns include reinvestment of dividends and interest. The example is hypothetical and provided for illustrative purposes only. It is not intended to represent a specific investment product. Indexes are unmanaged, do not incur management fees, costs and expenses and cannot be invested in directly. Past performance is no guarantee of future results.

The CD Wealth Formula

We help our clients reach and maintain financial stability by following a specific plan, catered to each client. 

Our focus remains on long-term investing with a strategic allocation while maintaining a tactical approach. Our decisions to make changes are calculated and well thought out, looking at where we see the economy is heading. We are not guessing or market timing. We are anticipating and moving to those areas of strength in the economy — and in the stock market. 

We will continue to focus on the fact that what really matters right now is time in the market, not out of the market. That means staying the course and continuing to invest, even when the markets dip, to take advantage of potential market upturns. We continue to adhere to the tried-and-true disciplines of diversification, periodic rebalancing and looking forward, while not making investment decisions based on where we have been.

It is important to focus on the long-term goal, not on one specific data point or indicator. Long-term fundamentals are what matter. In markets and moments like these, it is essential to stick to the financial plan. Investing is about following a disciplined process over time.

Sources: Capital Group, Carson, CNBC, Fidelity, Schwab

The Election May Bring Volatility, but the Market Doesn’t Care Who Wins

Stocks reached new highs again last week, the fifth week in a row that the S&P 500 has had positive returns. The S&P now has reached 46 new all-time highs this year, which ranks as the ninth-most ever — and we still have two and a half months to go.

The current bull market is 2 years old as of last Saturday, following a 25% drop in stocks in 2022 that coincided with a steep drop in bond returns as well. Since 1950, the average bull market has lasted more than 5 years and has gained more than 180%. Based on history, we know the market does not go up in a straight line, and plenty of upside remains.

The Bull Market Is Still Young

S&P 500 bull markets from 1950 to today

Sources: Carson Investment Research, YCharts 10/7/24. *Most recent new all-time high was on 9/30/24. 


For now, political uncertainty appears to be doing little to dampen enthusiasm for stocks. Strong economic growth has helped the S&P 500 reach its new highs; it is up over 20% for the year and is on track for the second straight year of double-digit gains.

Still, election anxiety may be on investors’ minds. The VIX, which measures market volatility, has risen about 25% since late September. Some of the increase is attributable to the election and concern that we may not know the outcome immediately following Election Day. Markets do not like uncertainty.

Every four years, investors may worry about what to do with their portfolio as the election nears. History shows that over the long term, the stock market tends to be relatively indifferent to who is in office.

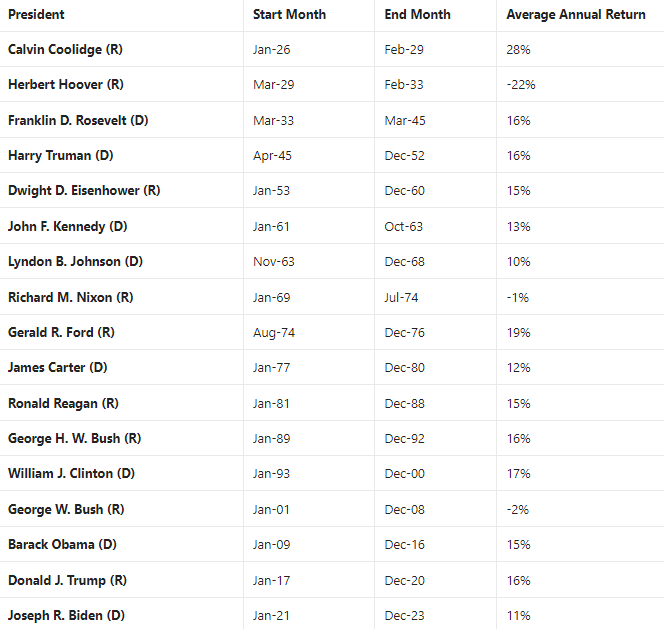
Since 1926, the market has seen negative returns only three times in 17 presidential administrations. One came during the Great Depression under Herbert Hoover, and another came during the Great Recession under George W. Bush. During Richard Nixon’s time in office, the U.S. suffered through the Vietnam War and two recessions — and suffered average losses of only 1% per year.

Chart showing average returns during last 17 presidencies.


Politics can bring out strong emotions and biases, but as we have said before, investors would be wise to tune out the noise and focus on the long-term fundamentals. Political opinions are best expressed at the polls, not through your portfolio. Historically speaking, election results have made almost no difference when it comes to long-term investment returns.

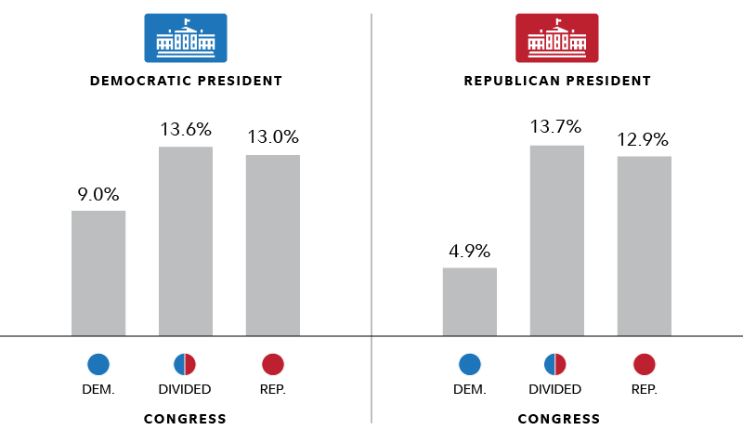
History also shows that stocks have done well regardless of which party is in control in Washington. Since 1933, there have been eight Democratic presidents and seven Republican presidents. The chart below shows how the market has performed on average under each scenario for the party in control of the White House and Congress. In that time, the worst average annual return was 11% — to the positive.

Chart showing market returns in different party scenarios.


Investors who allow political opinions to harm their investing discipline have missed out on above-average returns during presidents they don’t like.

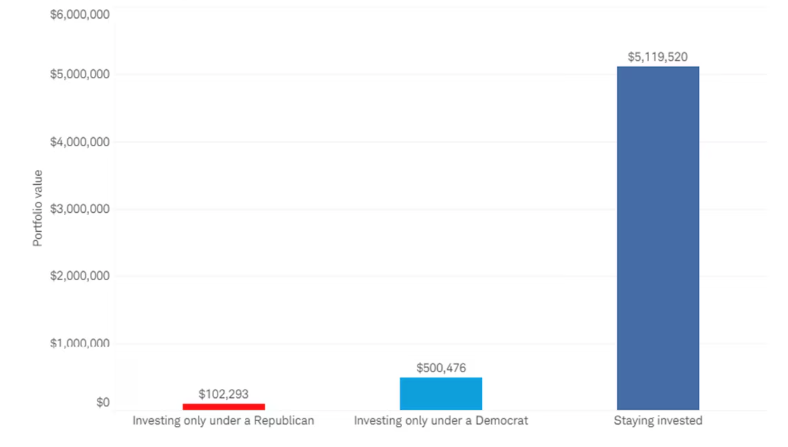
The chart below shows that if you invested $10,000 in 1961, it would have grown to more than $102,000 by 2023 if you invested only during a Republican presidency. If you invested the same $10,000 in 1961, that same investment would have grown to $500,000 if you invested only while a Democrat was in the White House. However, that $10,000 investment would be worth more than $5.1 million if you just stayed invested no matter who was in office.

Growth of $10,000 (1961-2023)

Chart showing how a $10,000 investment would have fared aince 1961 depending on behavior in regard to who is in office.
Sources: Schwab Center for Financial Research with data provided by Morningstar, Inc. The above chart shows what a hypothetical portfolio value would be if an investor invested $10,000 in a portfolio that tracks the Ibbotson U.S. Large Stock Index on Jan. 1, 1961, through the end of 2023 under three different scenarios. The first two scenarios are what would occur if an investor only invested when one particular party was president. The third scenario is what would occur if an investor had stayed invested through the entire period. The example is hypothetical and provided for illustrative purposes only. It is not intended to represent a specific investment product. Dividends and interest are assumed to have been reinvested, and the example does not reflect the effects of expenses, taxes or fees, and if it had, performance would have been substantially lower. Indexes are unmanaged, do not incur management fees, costs and expenses, and cannot be invested in directly. For additional information, see schwab.com/indexdefinitions. Past performance is no guarantee of future results.


Investors should not let their political opinions or emotions dictate their decisions. The markets really don’t care about the results or the daily micro-dramas in the presidential race. Markets are much more likely to be influenced by corporate earnings, economic data and monetary policy.

As James Carville said back in 1992, “It’s the economy, stupid.”

Unemployment remains near historic lows. Inflation has dropped from a post-pandemic high of 9% to 2.4%. The stock market is at new highs, and interest rates and energy prices are on the decline. Long-term investment strategies tend to perform well regardless of who occupies the White House.

Promo for an article titled What Investors Should Know About the Fed’s First Rate Cut Since 2020.

The CD Wealth Formula

We help our clients reach and maintain financial stability by following a specific plan, catered to each client. 

Our focus remains on long-term investing with a strategic allocation while maintaining a tactical approach. Our decisions to make changes are calculated and well thought out, looking at where we see the economy is heading. We are not guessing or market timing. We are anticipating and moving to those areas of strength in the economy — and in the stock market. 

Our focus remains on long-term investing with a strategic allocation while maintaining a tactical approach. Our decisions to make changes are calculated and well thought out, looking at where we see the economy is heading. We are not guessing or market timing. We are anticipating and moving to those areas of strength in the economy — and in the stock market. 

It is important to focus on the long-term goal, not on one specific data point or indicator. Long-term fundamentals are what matter. In markets and moments like these, it is essential to stick to the financial plan. Investing is about following a disciplined process over time.

Sources: BlackRock, Capital Group, Carson, CNBC, Dimensional Funds, Fidelity, Schwab

What Investors Should Know About the Fed’s First Rate Cut Since 2020

After another rough start to the month of September, stocks have rallied and have remained positive for the last three weeks. The S&P 500 has been up 10 out of the last 11 months, and all three major U.S. stock market indexes are near all-time highs.

The big story last month was the Fed’s decision to cut interest rates for the first time since March 2020, when Covid-19 shuttered most of the world’s economy. The Fed reduced interest rates by 50 basis points on Sept. 18. Although it was widely expected that the Fed would cut rates, questions remained about the size and timing.

Did the Fed’s decision have anything to do with the election?

The Fed made the cut in its final meeting before the election in November; its next meeting will be Nov. 7, two days after the election. The Fed has consistently and repeatedly stressed that political considerations do not factor into its decision-making, regardless of what some media reports may say.

“We never use our tools to support or oppose a political party, a politician, or any political outcome,” Chairman Jerome Powell said at the Fed’s July press conference. “Anything that we do before, during or after the election will be based on the data, the outlook, and the balance of risks, and not on anything else.”

The Fed has shifted its focus from the fight against inflation to the health of the job market. For much of the past few years, unemployment has been so low and inflation so high that the Fed could focus predominantly on reigning in inflation. Now, unemployment has risen above to 4.2% from a low of 3.4%, and the pace of new jobs being added each month has slowed.
Are rate cuts near all-time market highs normal?

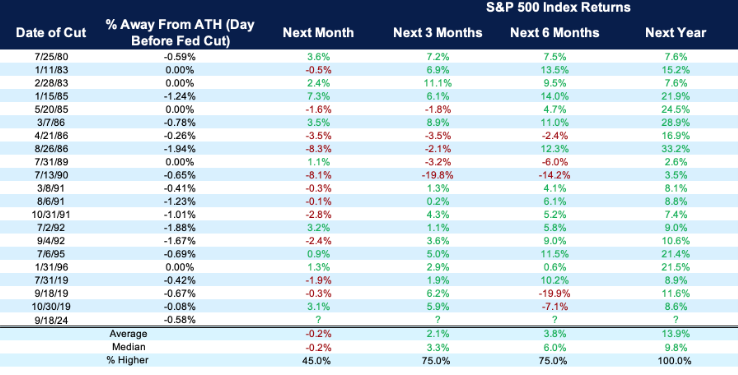
This is not the first time that the Fed has cut rates with the market at or near all-time highs. In fact, this most recently occurred in 2019. There have been 20 times that the Fed cut rates when the market was within 2% of all-time highs, and in each instance, stocks were higher a year later. Remember the adage: Don’t fight the Fed!

Fed Cuts Near All-Time Highs

S&P 500 returns after Fed cuts within 2% of an all-time high

Chart showing S&P 500 returns after Fed cuts within 2% of an all-time high.
Sources: Carson Investment Research, FactSet 9/18/24

Does this mean that the Fed thinks the economy is in trouble?

The economy continues to surprise to the upside. While the labor market has been cooling, it is important to remember that it is coming down from unusually high levels from the global pandemic. GDP growth for the last five years was revised from 9.4% to 10.7% and grew at 3% for the last quarter. Disposable income for households also was revised higher and as a result, the savings rate was revised up from 3.3% to 5.2% in the previous quarter.

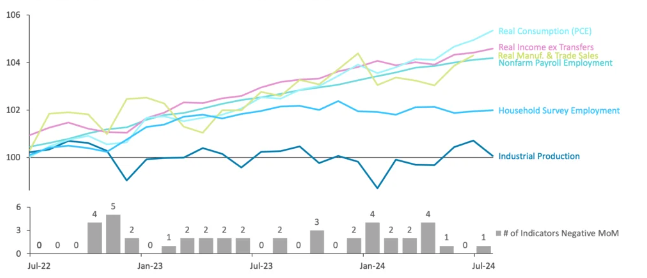
Corporate earnings are expected to grow at double digits for the year and are expected to grow 15% for 2025. Looking at the chart below, only one of the six indicators used by the National Bureau of Economic Research for recession tracking reflects a potential recession.

Recessionary Indicators

National Bureau of Economic Research recession indicators for the United States (normalized to July 2022)

Chart showing National Bureau of Economic Research recession indicators for the United States (normalized to July 2022).
Sources: Bureau of Labor Statistics, Bureau of Economic Analysis, Federal Reserve, U.S. Census Bureau, iCapital Investment Strategy with data based on availability as of Sept. 4, 2024. Note: Data as of July 2024 for all indicators except for Real Manufacturing & Trade Sales, which is as of June 2024. Data is subject to change based on potential updates to source database. Analysis looks at the six indicators used by the NBER to define a recession in the United States. For illustrative purposes only. Past performance is not indicative of future results. Future results are not guaranteed.

What do rate cuts mean for consumers and investors?

It is important to remember that the Fed controls very short-term rates only. The Fed does not set interest rates for mortgages, CDs, or bonds. However, it can influence these rates through its actions. Consumers may feel the impact most immediately with lower interest payments on debt that is tied to the prime rate, like credit cards or auto loans.

Interest rates on longer-term debt, like mortgages, have already been falling in anticipation of lower rates coming. It is important to note that mortgage rates won’t keep pace with Fed rate cuts, and the days of 3% mortgages are a long way off — if they ever come again.

Investors have been anxious for the Fed to begin cutting rates. There have been 13 rate-cut cycles since World War II, with an average S&P 500 return after the first rate cut of 14%. It is not just stocks that stand to benefit from lower rates. As the Fed lowers rates, cash yields will drop in tandem. Investors faced with lower rates on cash have been moving into stocks and bonds to replace the lost yield.

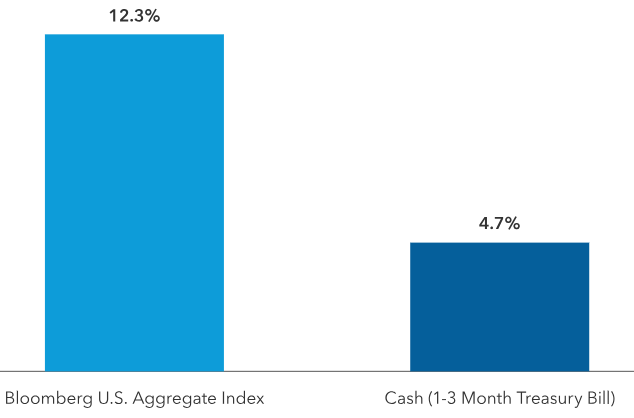
Historically, bonds have been at their strongest in periods of rate cuts since bond prices rise as yields fall. Average returns for the U.S. Aggregate Bond Index have outpaced cash proxies in rate-cutting periods over the last 40 years.

Falling Rates Have Supported Bond Returns

Average annualized monthly returns during rate-cutting cycles

Chart showing how Falling Rates Have Supported Bond Returns.
Sources: Capital Group, Bloomberg. Based on average monthly returns during rate-cutting periods from September 1984 through Sept. 11, 2024.

Where do we go from here?

The market is pricing in that by this time next year, the Fed will have cut interest rates eight to 10 times, and the benchmark rate will be at 3%. That would be much lower than today’s rates but still higher than any time from 2009 to 2021. 

October typically has been the worst month during an election year, and we wouldn’t be surprised to see some volatility during the month. However, the good news is that November and December do quite well in election years as the uncertainty of the election is removed. Investors have been rewarded for staying invested amid the constant negative sentiment and worry.

The CD Wealth Formula

We help our clients reach and maintain financial stability by following a specific plan, catered to each client. 

Our focus remains on long-term investing with a strategic allocation while maintaining a tactical approach. Our decisions to make changes are calculated and well thought out, looking at where we see the economy is heading. We are not guessing or market timing; we are anticipating and moving to those areas of strength in the economy — and in the stock market. 

We will continue to focus on the fact that what really matters right now is time in the market, not out of the market. That means staying the course and continuing to invest, even when the markets dip, to take advantage of potential market upturns. We continue to adhere to the tried-and-true disciplines of diversification, periodic rebalancing and looking forward, while not making investment decisions based on where we have been.

It is important to focus on the long-term goal, not on one specific data point or indicator. Long-term fundamentals are what matter. In markets and moments like these, it is essential to stick to the financial plan. Investing is about following a disciplined process over time.

Sources: Capital Group, Carson, Fidelity, NBER

The Market’s Recovery Puts August Pullback in the Rearview Mirror

Last week, stocks had their best week of the year. The S&P 500 rose eight days in a row, the first eight-day streak since November. In the last four years that saw an eight-day win streak, the average return was over 26% for the year.

As of now, the S&P 500 is up almost 18% through mid-August.

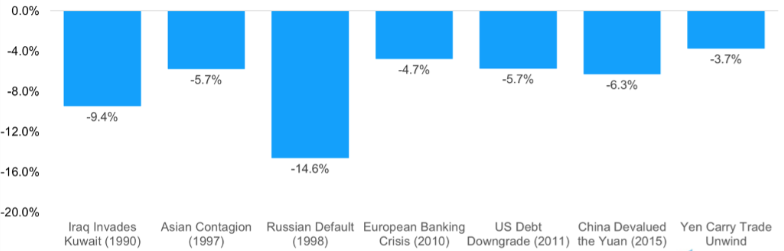
It wasn’t that long ago that the stock market saw a pullback that led some investors to a mild freak-out in anticipation of a worst-case scenario. The headlines were dominated by fears of a recession, the Fed being behind the curve on interest rate cuts and the yen carry trade ending.

Two weeks later, stocks are back near all-time highs, led by a broad-based rally of small caps, large-cap stocks, mega-cap stocks and international stocks. A run of favorable economic data across producer price index (PPI), consumer price index (CPI), retail sales and jobless claims is driving the rally.

More often than any other month, August is when we tend to see these types of out-of-the-blue events.

As the chart shows, this year saw the seventh-largest August crisis that caused extreme fear and volatility since 1990. The good news: Investors got through all of them, and we don’t expect this time — or the next time — to be any different.

Even the best years in the market have bad days and scary headlines. Does this mean that we are completely out of the woods with regards to market weakness or volatility? Not at all; the months leading up to elections often can be volatile.

There’s Something About August

S&P 500 returns in volatile Augusts (1990-present)

Chart showing S&P 500 returns in volatile Augusts (1990-present).
Source: Carson Investment Research, FactSet 8/9/24 (1990-present)

The last few weeks have been a good reminder of the adage that what matters is time in the market and not timing the market. The worst time to sell is in a market panic, no matter how long or brief that panic may be. If you get scared and decide to get out of the market, you probably will miss some of the best days of the year.

If you had invested $10,000 into the S&P 500 in 2004 and stayed invested over that entire time, the investment would be worth almost $64,000. If you tried to time the market or got scared and got out during one of the above August scares, and you missed the best 10 days, the return would be less than half that total. It gets worse from there.

What we see so often is that once an investor decides to sell out of the market, it becomes very difficult to get back in.

Fear takes over, and you think that the market can only go one direction — down. Fearful investors assume that even if the market bounces, they can’t get back in as they were by buying back in at a higher level than where they sold.

If you wait to get more clarity or less uncertainty, you will probably miss the best days — and that will cost you in the long run.

Time In the Market, Not Timing the Market

Performance of $10,000 invested in the S&P 500 the past 20 years (2004-2023)

Chart showing the performance of $10,000 invested in the S&P 500 the past 20 years (2004-2023).
Source: Carson Investment Research, JPMorgan Asset Management

The current economy’s underlying fundamentals are sound, but a large disconnect remains between the stock market, the economy and people’s sentiments about the economy. The job market has started to cool off since the remarkable strength of the pandemic. The number of job openings continues to trend downward.

Inflation has cooled significantly, but not quite to the level that the Fed wants to see. What’s more, consumer prices are still higher than they were several years ago, and people continue to feel it in their pocketbooks. Food prices have risen more than 25% since January 2020.

It also costs more to borrow money today than it used to. We became used to low interest rates for homes and credit cards. High rates combined with higher home prices have made buying a home much harder.

Finally, most people who are invested in stocks are invested through their 401K or retirement accounts. The growth in the market is not helping those individuals with increased costs of living, which may be why most don’t feel so great about the current economy even as the market hits new highs.

It is so important to keep your eye on the prize and focus on the big picture; economic growth remains strong, and the real economy continues to grow, which in turn, fuels the market to move higher.

The CD Wealth Formula

We help our clients reach and maintain financial stability by following a specific plan, catered to each client. 

Our focus remains on long-term investing with a strategic allocation while maintaining a tactical approach. Our decisions to make changes are calculated and well thought out, looking at where we see the economy is heading. We are not guessing or market timing. We are anticipating and moving to those areas of strength in the economy — and in the stock market. 

We will continue to focus on the fact that what really matters right now is time in the market, not out of the market. That means staying the course and continuing to invest, even when the markets dip, to take advantage of potential market upturns. We continue to adhere to the tried-and-true disciplines of diversification, periodic rebalancing and looking forward, while not making investment decisions based on where we have been.

It is important to focus on the long-term goal, not on one specific data point or indicator. Long-term fundamentals are what matter. In markets and moments like these, it is essential to stick to the financial plan. Investing is about following a disciplined process over time.

Sources: Carson, Fidelity, JP Morgan, Opco

Promo for an article titled Turning Investment Losses into Gains: The Art of Tax-Loss Harvesting.

This material contains an assessment of the market and economic environment at a specific point in time and is not intended to be a forecast of future events, or a guarantee of future results. Forward-looking statements are subject to certain risks and uncertainties. Actual results, performance, or achievements may differ materially from those expressed or implied. Information is based on data gathered from what we believe are reliable sources.

Using diversification as part of your investment strategy neither assures nor guarantees better performance and cannot protect against loss of principal due to changing market conditions.

Past performance is not a guarantee of future results.

The opinions expressed in this commentary are those of the author and may not necessarily reflect those held by Kestra Investment Services, LLC or Kestra Advisory Services, LLC. This is for general information only and is not intended to provide specific investment advice or recommendations for any individual. It is suggested that you consult your financial professional, attorney, or tax advisor with regard to your individual situation.

Securities offered through Kestra Investment Services, LLC (Kestra IS), member FINRA/SIPC. Investment Advisory Services offered through Kestra Advisory Services, LLC (Kestra AS) an affiliate of Kestra IS. CD Wealth Management and Bluespring Wealth Partners LLC* are affiliates of Kestra IS and Kestra AS.  Investor Disclosures: https://bit.ly/KF-Disclosures

*Bluespring Wealth Partners, LLC acquires and supports high quality investment adviser and wealth management companies throughout the United States.

Fidelity Investments and Fidelity Institutional® (together “Fidelity”) is an independent company, unaffiliated with Kestra Financial or CD Wealth Management. Fidelity is a service provider to both. There is no form of legal partnership, agency affiliation, or similar relationship between your financial advisor and Fidelity, nor is such a relationship created or implied by the information herein. Fidelity has not been involved with the preparation of the content supplied by CD Wealth Management and does not guarantee, or assume any responsibility for, its content. Fidelity Investments is a registered service mark of FMR LLC. Fidelity Institutional provides clearing, custody, or other brokerage services through National Financial Services LLC or Fidelity Brokerage Services LLC, Members NYSE, SIPC.

What Investors Should Know About This Week’s Market Pullback

Investors woke up Monday morning to a sudden global panic, cratering the value of stocks, currencies and even cryptocurrencies. The Dow fell over 1,200 points at the open, the S&P 500 dropped over 200 points, and the NASDAQ was down over 1,000 points, more than a 6% pullback. Japan’s Nikkei Index fell more than 12%, its largest one-day drop in almost 40 years, following an interest rate hike by the Bank of Japan last week.

The NASDAQ is officially in correction mode, down more than 10% from its all-time high. The S&P 500 is down 9% from its recent high, set three weeks ago, and it has fallen the last three weeks. This is only the second pullback of 5% or more this year; most years see more than three 5% pullbacks on average. 

As great as 2023 was, investors should remember we saw a 10% correction from late July until October. On average over the last 70+ years, the market has seen a 10% correction at least once per calendar year — and a 15% correction every 18 months.

Volatility Is the Toll We Pay To Invest

S&P 500 per year (1950-2022)

A chart showing dips and corrections in the S&P 500 from 1950 to 2022.

It is important to look at what caused the sudden market volatility and the recent pullback in the stock market:

1. Last week’s jobs report caused concerns of a recession. A few data points last week showed signs of a weakening economy: jobless claims at their highest level in a year, weak manufacturing data, Friday’s non-farm payroll number missing by a large margin and the unemployment rate at 4.3%, its highest level since 2022. While the labor market has cooled, the economy remains on good footing, as preliminary GDP numbers were strong. 

2. The Fed did not reduce interest rates and will wait until September. We have been seeing improving data showing inflation is under control. Higher rates have impacted the housing market and small business investment. The Fed has two mandates: keep prices under control and maintain full employment. Ten-year Treasury yields have fallen below 4%, and for the first time in more than two years, the yield curve is no longer inverted. The bond market is signaling that it is time for the Fed to begin cutting interest rates — and maybe that it has waited too long.

3. Carry trade may be ending. The Bank of Japan raised interest rates for the first time in 17 years, to .25% from 0%. It also acknowledged that more rate hikes may be coming this year. Japanese investors have been borrowing money at zero rates and investing those monies into higher-yielding or riskier assets both domestically and overseas. This is called a “carry trade.” The rate hike in Japan was a taken as a signal that the carry trade strategy is approaching its end, and investors are now reversing their positions. As they reverse their trades, they are selling those riskier assets, such as U.S. stocks, to pay off the borrowed money in Japan. It is unknown how long the unwinding of the carry trade may last and how much more potential downside there may be.

4. Warren Buffett disclosed that he sold half of his long-term position in AAPL. While we don’t know the entire reason Buffett unloaded half of his Apple stock, the stock remains his largest holding at over $84 billion. This could be positioning for a higher capital gains rate in the future, or it could be market valuation — or his opinion of the Apple stock valuation. Either way, the disclosure over the weekend on top of weaker jobs data and what was happening in Japan caused additional stress to the trading of the Magnificent Seven stocks.

5. The hype over AI is showing cracks. The S&P 500 and NASDAQ are both up more than 9% on the year, even after the sharp sell-off. Stocks have benefited from strong corporate earnings and continued excitement over artificial intelligence’s growth and potential. Nvidia has been the clear leader for AI chips. Rumors began circulating Monday that it is delaying its next-generation AI chips by at least three months, which could alter its earnings as well as other mega-cap tech stocks such as Microsoft, Google and Meta.

It is important to remember that market pullbacks are normal and that the market does not go up in a straight line.

The average market pullback in a calendar year going back to 1980 is more than 14% in any one year. But what you notice in the chart below is that there are many more positive years than negative years in the S&P 500, and only in one instance — the Great Financial Crisis — have we seen multiple down years in a row. 

We repeat the drumbeat that what matters is time in the market and not time out of the market. While we have seen increased market volatility, this is normal and part of long-term investing in the stock market.

Putting 2024 in Perspective

S&P 500 Index max pullback per calendar year

A graphic showing the S&P 500 Index max pullback per calendar year since 1980.
Source: Carson, YCharts 8/5/2024 (1980-current)

The CD Wealth Formula

We help our clients reach and maintain financial stability by following a specific plan, catered to each client. 

Our focus remains on long-term investing with a strategic allocation while maintaining a tactical approach. Our decisions to make changes are calculated and well thought out, looking at where we see the economy is heading. We are not guessing or market timing. We are anticipating and moving to those areas of strength in the economy — and in the stock market. 

We will continue to focus on the fact that what really matters right now is time in the market, not out of the market. That means staying the course and continuing to invest, even when the markets dip, to take advantage of potential market upturns. We continue to adhere to the tried-and-true disciplines of diversification, periodic rebalancing and looking forward, while not making investment decisions based on where we have been.

It is important to focus on the long-term goal, not on one specific data point or indicator. Long-term fundamentals are what matter. In markets and moments like these, it is essential to stick to the financial plan. Investing is about following a disciplined process over time.

Sources: AAM, Carson, CNBC, Fortune, Forbes, Washington Post

Promo for article titled Here's Why Investors Should Keep Politics Out of the Portfolio.

This material contains an assessment of the market and economic environment at a specific point in time and is not intended to be a forecast of future events, or a guarantee of future results. Forward-looking statements are subject to certain risks and uncertainties. Actual results, performance, or achievements may differ materially from those expressed or implied. Information is based on data gathered from what we believe are reliable sources.

Using diversification as part of your investment strategy neither assures nor guarantees better performance and cannot protect against loss of principal due to changing market conditions.

Past performance is not a guarantee of future results.

The opinions expressed in this commentary are those of the author and may not necessarily reflect those held by Kestra Investment Services, LLC or Kestra Advisory Services, LLC. This is for general information only and is not intended to provide specific investment advice or recommendations for any individual. It is suggested that you consult your financial professional, attorney, or tax advisor regarding your individual situation.

Securities offered through Kestra Investment Services, LLC (Kestra IS), member FINRA/SIPC. Investment Advisory Services offered through Kestra Advisory Services, LLC (Kestra AS) an affiliate of Kestra IS. CD Wealth Management and Bluespring Wealth Partners LLC* are affiliates of Kestra IS and Kestra AS.

Investor Disclosures: https://bit.ly/KF-Disclosures

*Bluespring Wealth Partners, LLC acquires and supports high quality investment adviser and wealth management companies throughout the United States.

Here’s Why Investors Should Keep Politics Out of the Portfolio

We are less than 100 days from Election Day. Whenever a presidential election rolls around, it is common to hear it described as “unprecedented.” Presidential elections always add an extra element of uncertainty to investing. On top of assessing the path of the Federal Reserve, the stability of profits and the consumer, investors must grapple with a barrage of headlines about the election.

Uncertainty can create opportunity. Investors often make their worst mistakes during uncertain times, and it can sometimes take years for their portfolios to recover.

As seen in the chart below, many geopolitical events have impacted portfolios in the short term over the last 120 years. Over the long run, however, the market has trended higher.

Investors sometimes get tunnel vision when it comes to the stock market and may only see what is right in front of them: an election, war or a pandemic, for example. When you stretch out your time horizon, the odds move in your favor; roughly 75% of single years have positive returns, nearly 90% of five-year periods are positive, and 100% of 20-year periods are positive!

Even With Bad News, Stocks Tend To Go Higher

Chart showing how the market has performed through various geopolitical events.
Source: Carson Investment Research, FactSet 7/26/2024

Political opinions are best expressed at the polls — not through the portfolio. It is crucial to keep your political feelings from overruling your investing strategy. Investors who allow political opinions to harm their investing discipline may have missed out on above-average returns during political administrations they may not like.

With the intensity of feelings on both sides, it is natural for investors to assume that the news of the day — the election’s eventual outcome — could have major impacts on sentiment and prices in the financial markets. 

The stock market is not partisan. Although popular myths suggest that one party or the other is better for market returns, historical data shows otherwise.

The S&P 500 has averaged positive returns under every partisan combination, as the chart below shows. There also is evidence that a divided government has correlated with stronger market returns — probably because gridlock creates less policy uncertainty, and markets do not like uncertainty.

If you had invested $1,000 in the S&P 500 starting in 1953 and only invested under Republican presidents, you would have just under $30,000 today. If you did the same thing but for only Democrat presidents, you would have just over $60,000. However, if you stayed invested no matter which party was in office, your $1,000 investment would be worth close to $1.7 million today. 

No matter which side you sit on, this election cycle is likely to bring more surprising headlines and plenty of emotional ups and downs. It can be tempting to put your money where your convictions are — whether you are optimistic or pessimistic about the November election — but history shows that doing so is not the best economic move for your long-term financial health.

Average Annual S&P 500 Performance

(1933-2022, excluding 2001-2002)

Chart showing S&P performance under each party's leadership.
Past performance is no guarantee of future results. Data excludes 2001-2002 due to Senator Jeffords changing parties in 2001. Calendar-year performance from 1933 through 2022. Source: Strategas Research Partners, as of Nov. 5, 2023.

Despite heightened political uncertainty, the economic backdrop remains positive. Market moves are more likely to be driven by market and economic fundamentals like corporate earnings, interest rates and other economic factors. GDP remains strong, the Fed is likely to reduce interest rates, and corporate earnings are expected to grow at double digits in 2024. 

Over the past 40 years, there has been only one instance when market returns were negative 12 months after an election — the tech bubble in 2000. This is not to downplay the importance of an election, but instead to remind us that the economy does not change course based on an election result. 

Through good times and bad, economic progress and the ingenuity of American companies have led to innovation, increased productivity and earnings growth — ultimately driving markets higher. Once political uncertainty is out of the way, markets tend to return to focusing on fundamentals, and right now, the fundamentals look pretty good.

The CD Wealth Formula

We help our clients reach and maintain financial stability by following a specific plan, catered to each client. 

Our focus remains on long-term investing with a strategic allocation while maintaining a tactical approach. Our decisions to make changes are calculated and well thought out, looking at where we see the economy is heading. We are not guessing or market timing. We are anticipating and moving to those areas of strength in the economy — and in the stock market. 

We will continue to focus on the fact that what really matters right now is time in the market, not out of the market. That means staying the course and continuing to invest, even when the markets dip, to take advantage of potential market upturns. We continue to adhere to the tried-and-true disciplines of diversification, periodic rebalancing and looking forward, while not making investment decisions based on where we have been.

It is important to focus on the long-term goal, not on one specific data point or indicator. Long-term fundamentals are what matter. In markets and moments like these, it is essential to stick to the financial plan. Investing is about following a disciplined process over time.

Sources: Capital Group, Carson, JP Morgan, Strategas Research

Promo for an article titled Here's Why Patience May Be an Investor's Greatest Asset.

This material contains an assessment of the market and economic environment at a specific point in time and is not intended to be a forecast of future events, or a guarantee of future results. Forward-looking statements are subject to certain risks and uncertainties. Actual results, performance, or achievements may differ materially from those expressed or implied. Information is based on data gathered from what we believe are reliable sources.

Using diversification as part of your investment strategy neither assures nor guarantees better performance and cannot protect against loss of principal due to changing market conditions.

Past performance is not a guarantee of future results.

The opinions expressed in this commentary are those of the author and may not necessarily reflect those held by Kestra Investment Services, LLC or Kestra Advisory Services, LLC. This is for general information only and is not intended to provide specific investment advice or recommendations for any individual. It is suggested that you consult your financial professional, attorney, or tax advisor with regard to your individual situation.

Securities offered through Kestra Investment Services, LLC (Kestra IS), member FINRA/SIPC. Investment Advisory Services offered through Kestra Advisory Services, LLC (Kestra AS) an affiliate of Kestra IS. CD Wealth Management and Bluespring Wealth Partners LLC* are affiliates of Kestra IS and Kestra AS.  Investor Disclosures: https://bit.ly/KF-Disclosures

*Bluespring Wealth Partners, LLC acquires and supports high quality investment adviser and wealth management companies throughout the United States.

Fidelity Investments and Fidelity Institutional® (together “Fidelity”) is an independent company, unaffiliated with Kestra Financial or CD Wealth Management. Fidelity is a service provider to both. There is no form of legal partnership, agency affiliation, or similar relationship between your financial advisor and Fidelity, nor is such a relationship created or implied by the information herein. Fidelity has not been involved with the preparation of the content supplied by CD Wealth Management and does not guarantee, or assume any responsibility for, its content. Fidelity Investments is a registered service mark of FMR LLC. Fidelity Institutional provides clearing, custody, or other brokerage services through National Financial Services LLC or Fidelity Brokerage Services LLC, Members NYSE, SIPC.

Our Top Articles of 2024 So Far: Did You Miss Any?

Now that we’re past the halfway point of 2024, we wanted to take this occasion to look back at the articles we’ve produced for our clients so far this year and share the five most popular pieces, in case you missed any of them — or if you want to revisit and share them with friends and family.

Twice a month, we thoughtfully craft these pieces with our clients in mind, broaching subjects we think are relevant and interesting. This is not syndicated content. We want you to find value in these letters — especially in times like these.

+++

Senior couple, documents and sign contract for life insurance or home mortgage. Discussion, signature and retired elderly man and woman signing legal paperwork for will or loan application together.

1. Understanding How a Living Trust Can Help Your Estate Planning

June 20 | A living trust is a flexible, popular tool that allows the estate to avoid probate and lets you control asset distribution after your death. Read more

+++

Stock market data with uptrend vector. 3d render.

2. Another Milestone for the Dow: What Could Happen Next?

May 23 | The Dow’s rise to 40,000 is a reminder that when it comes to investing, patience is the key. Read more

+++

Index on a screen.

3. Here’s Why Investors Shouldn’t Panic Over the Market’s New Year’s Hangover

Jan. 12 | We talk regularly about not timing the market, and we don’t see these circumstances any differently. Read more

+++

Smiling mature couple meeting with bank manager for investment. Beautiful mid adult woman with husband listening to businessman during meeting in conference room in modern office. Happy middle aged couple meeting loan advisor to buy a new home.

4. Here’s How We’re Rebalancing the Portfolio as We Enter the Second Quarter

March 15 | We think much of the pain from rising interest rates is behind us — and the key to navigating volatility remains being in a diversified portfolio. Read more

+++

Male manager businessmen are looking at the tablet screen with the company's financial information and he is tense about the performance.

5. Investor Outlook: A Strong May, the First 100 Trading Days and 4 Scams to Watch

June 6  |  S&P 500 companies are enjoying their best earnings season in almost two years. Read more

+++

P.S. Looking for more? Here are the five articles that are most popular this year on our website (no matter when they were published).

1. The Importance of Compound Interest and Tax Planning on Your Portfolio (Sept. 8, 2022)
2. You’ve inherited an IRA. What happens next? (April 14, 2022)
3. Understanding the 10-Year Treasury and Why It Matters to Investors (Nov. 2, 2023)
4. Understanding How a Living Trust Can Help Your Estate Planning (June 20, 2024)
5. Before you sell for a loss, make sure you know the wash-sale rule (May 5, 2022)

+++

The CD Wealth Formula

We help our clients reach and maintain financial stability by following a specific plan, catered to each client. 

Our focus remains on long-term investing with a strategic allocation while maintaining a tactical approach. Our decisions to make changes are calculated and well thought out, looking at where we see the economy is heading. We are not guessing or market timing. We are anticipating and moving to those areas of strength in the economy — and in the stock market. 

We will continue to focus on the fact that what really matters right now is time in the market, not out of the market. That means staying the course and continuing to invest, even when the markets dip, to take advantage of potential market upturns. We continue to adhere to the tried-and-true disciplines of diversification, periodic rebalancing and looking forward, while not making investment decisions based on where we have been.

It is important to focus on the long-term goal, not on one specific data point or indicator. Long-term fundamentals are what matter. In markets and moments like these, it is essential to stick to the financial plan. Investing is about following a disciplined process over time.

Promo for an article titled Here's Why Patience May Be an Investor's Greatest Asset.

This material contains an assessment of the market and economic environment at a specific point in time and is not intended to be a forecast of future events, or a guarantee of future results. Forward-looking statements are subject to certain risks and uncertainties. Actual results, performance, or achievements may differ materially from those expressed or implied. Information is based on data gathered from what we believe are reliable sources.

Using diversification as part of your investment strategy neither assures nor guarantees better performance and cannot protect against loss of principal due to changing market conditions.

Past performance is not a guarantee of future results.

The opinions expressed in this commentary are those of the author and may not necessarily reflect those held by Kestra Investment Services, LLC or Kestra Advisory Services, LLC. This is for general information only and is not intended to provide specific investment advice or recommendations for any individual. It is suggested that you consult your financial professional, attorney, or tax advisor with regard to your individual situation.

Securities offered through Kestra Investment Services, LLC (Kestra IS), member FINRA/SIPC. Investment Advisory Services offered through Kestra Advisory Services, LLC (Kestra AS) an affiliate of Kestra IS. CD Wealth Management and Bluespring Wealth Partners LLC* are affiliates of Kestra IS and Kestra AS.  Investor Disclosures: https://bit.ly/KF-Disclosures

*Bluespring Wealth Partners, LLC acquires and supports high quality investment adviser and wealth management companies throughout the United States.

Fidelity Investments and Fidelity Institutional® (together “Fidelity”) is an independent company, unaffiliated with Kestra Financial or CD Wealth Management. Fidelity is a service provider to both. There is no form of legal partnership, agency affiliation, or similar relationship between your financial advisor and Fidelity, nor is such a relationship created or implied by the information herein. Fidelity has not been involved with the preparation of the content supplied by CD Wealth Management and does not guarantee, or assume any responsibility for, its content. Fidelity Investments is a registered service mark of FMR LLC. Fidelity Institutional provides clearing, custody, or other brokerage services through National Financial Services LLC or Fidelity Brokerage Services LLC, Members NYSE, SIPC.

Investor Outlook: A Strong May, the First 100 Trading Days and 4 Scams to Watch

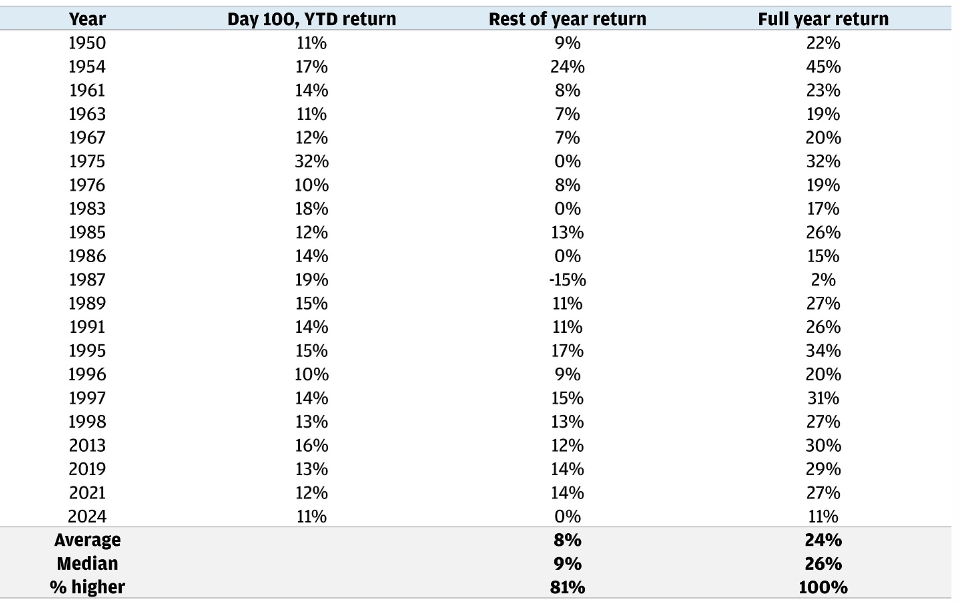
We are more than 100 trading days into the year, and the S&P 500 is up over 10% for the year. Since 1950, whenever the S&P 500 has gained at least 10% in the first 100 trading days, stocks have closed out the full year with an average return of about 25%.

At this time last year, the S&P 500 was up over 8% and closed out the year with a gain of almost 25%. So far, 2024 has seen more than 25 record highs. During years in which the S&P 500 reaches a new high, it usually makes around 30 new highs on average. During years when there have been this many new highs this early in the year, the full year has typically made more than 50 new highs.

100 Days In: Strong Returns Tend to Signal More Strength Ahead

S&P 500 returns after a 10% rally 100 trading days into the year

Chart showing full year returns when May has been 10% up or more since 1950.
Sources: Bloomberg Finance L.P., J.P. Morgan. Data as of May 23, 2024. Past performance is not indicative of future results. It is not possible to invest directly in an index.

The month of May finished strong, with the S&P 500 up almost 5%, erasing the April market swoon. S&P 500 companies are enjoying their best earnings season in almost two years, growing profits 6% over the prior year. Every sector but healthcare had positive earnings growth.

Even more important is that profit margins (how much profit a company makes from each dollar of sales) are around 12% for the quarter. Strong earnings growth is good for stocks and helps support the rising prices we have seen to start the year. 

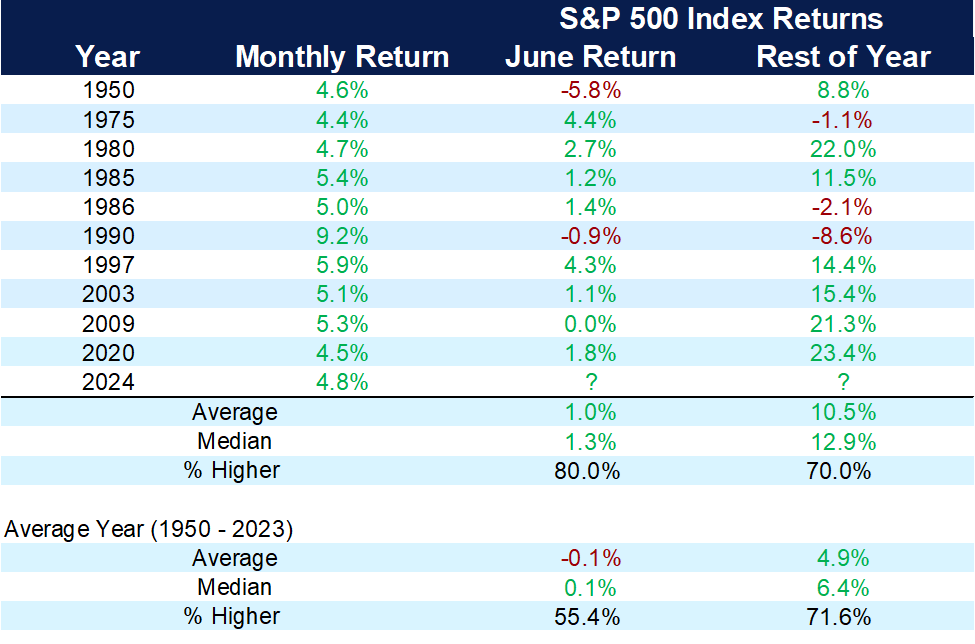
The chart below shows how the market has fared following a strong May going back to 1950. This is the 11th time since 1950 that May was up over 4%, and in those occurrences, the average return for the rest of the year has been over 10%.

A Big May Could Have Bulls Smiling

S&P 500 after >4% gain in May

Chart showing S&P 500 returns after strong showings in May.
Sources: Carson Investment Research, FactSet 6/3/2024.

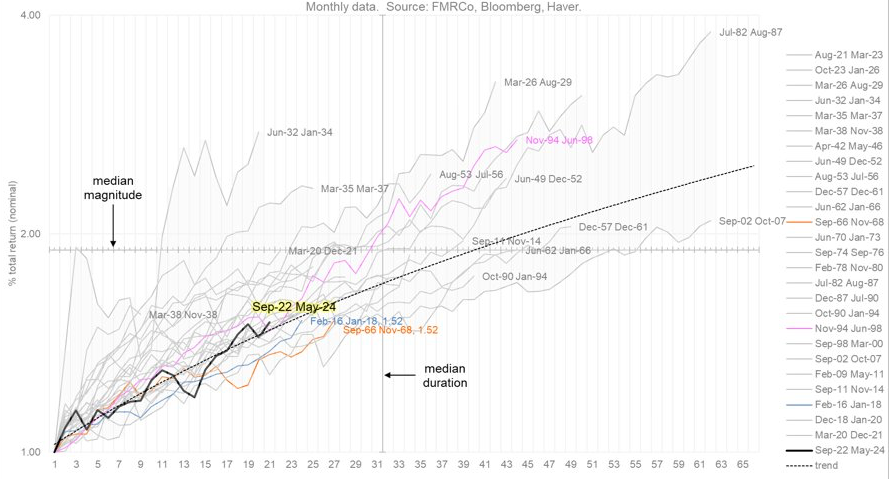
The current bull market cycle is 20 months old and has produced a 53% gain. By historical standards, the median bull market cycle has been 30 months and produced 90% gains over the past 100 years.

It is understandable to worry about the strength of the market following the run that we have had over the last 19 months. Remember, this market rally has happened with higher rates and sticky inflation. If the Fed were to reduce rates, that would be considered another positive for the market in the second half of the year.

Cyclical Bull Markets

Chart showing the cyclical nature of recent bull markets.
Sources: FMRCo, Bloomberg, Haver Analytics, FactSet. Data as of 6/2/2024. Past performance is no guarantee of future results.

The strong market in the last few years has led to a growth in net worth for those who were invested in the stock market. The Magnificent Seven stocks have continued to lead the market higher, driven by advancements in artificial intelligence. Many positives will come from AI’s growth, but at the same time, financial scams using AI tools and sophisticated technology are making things harder on consumers.

Financial crimes are on their way up and may be at a crisis level. Scams may come in the form of a text or email you receive that is purported to be from Apple, Amazon or PayPal — or even from someone you know who has a can’t-miss investment idea.

Here are four financial scams to be aware of in 2024:

1. Grandparent scam: This scam targets people by suggesting that a family member is in immediate jeopardy. Such scams are becoming more sophisticated with advanced technology, as thieves can capture a voice recording and generate an imitation version of your voice. Remember: Do not answer unknown calls, allowing someone to capture a recording of your voice.

2. Romance scam: An increasingly common way people take money from others involves creating a false online relationship and conning the other person into giving them money. A new version of this scam includes conning the fake romantic interest into investing in cryptocurrency or sending with gift cards.

3. Cryptocurrency scam: This is now the most common type of scam with total losses of more than $4 billion. 

4. Employment scams: In this scam, a fake employer sends you an email or text to gather information and obtain your personal identity. Do not click on the link from an unexpected text about a job opportunity.

Remember, you can’t be too careful today when it comes to protecting your identity and your data. Artificial intelligence will continue to evolve and make the battle more challenging.

If you do get caught in a scam, don’t be ashamed. Act on it by reporting it to your family, you financial advisor, your banks and the AARP. The faster you address the issue, the faster you can get it resolved. 

We are a safe spot for you and your family if you feel like you have been scammed. Call your team at CD Wealth right away, and we will help guide you.

The CD Wealth Formula

We help our clients reach and maintain financial stability by following a specific plan, catered to each client. 

Our focus remains on long-term investing with a strategic allocation while maintaining a tactical approach. Our decisions to make changes are calculated and well thought out, looking at where we see the economy is heading. We are not guessing or market timing. We are anticipating and moving to those areas of strength in the economy — and in the stock market. 

We will continue to focus on the fact that what really matters right now is time in the market, not out of the market. That means staying the course and continuing to invest, even when the markets dip, to take advantage of potential market upturns. We continue to adhere to the tried-and-true disciplines of diversification, periodic rebalancing and looking forward, while not making investment decisions based on where we have been.

It is important to focus on the long-term goal, not on one specific data point or indicator. Long-term fundamentals are what matter. In markets and moments like these, it is essential to stick to the financial plan. Investing is about following a disciplined process over time.

Sources: Carson, CNBC, Fidelity, JP Morgan

Promo for an article titled Another Milestone for the Dow: What Could Happen Next?

This material contains an assessment of the market and economic environment at a specific point in time and is not intended to be a forecast of future events, or a guarantee of future results. Forward-looking statements are subject to certain risks and uncertainties. Actual results, performance, or achievements may differ materially from those expressed or implied. Information is based on data gathered from what we believe are reliable sources.

Using diversification as part of your investment strategy neither assures nor guarantees better performance and cannot protect against loss of principal due to changing market conditions.

Past performance is not a guarantee of future results.

The opinions expressed in this commentary are those of the author and may not necessarily reflect those held by Kestra Investment Services, LLC or Kestra Advisory Services, LLC. This is for general information only and is not intended to provide specific investment advice or recommendations for any individual. It is suggested that you consult your financial professional, attorney, or tax advisor with regard to your individual situation.

Securities offered through Kestra Investment Services, LLC (Kestra IS), member FINRA/SIPC. Investment Advisory Services offered through Kestra Advisory Services, LLC (Kestra AS) an affiliate of Kestra IS. CD Wealth Management and Bluespring Wealth Partners LLC* are affiliates of Kestra IS and Kestra AS.  Investor Disclosures: https://bit.ly/KF-Disclosures

*Bluespring Wealth Partners, LLC acquires and supports high quality investment adviser and wealth management companies throughout the United States.

Fidelity Investments and Fidelity Institutional® (together “Fidelity”) is an independent company, unaffiliated with Kestra Financial or CD Wealth Management. Fidelity is a service provider to both. There is no form of legal partnership, agency affiliation, or similar relationship between your financial advisor and Fidelity, nor is such a relationship created or implied by the information herein. Fidelity has not been involved with the preparation of the content supplied by CD Wealth Management and does not guarantee, or assume any responsibility for, its content. Fidelity Investments is a registered service mark of FMR LLC. Fidelity Institutional provides clearing, custody, or other brokerage services through National Financial Services LLC or Fidelity Brokerage Services LLC, Members NYSE, SIPC.